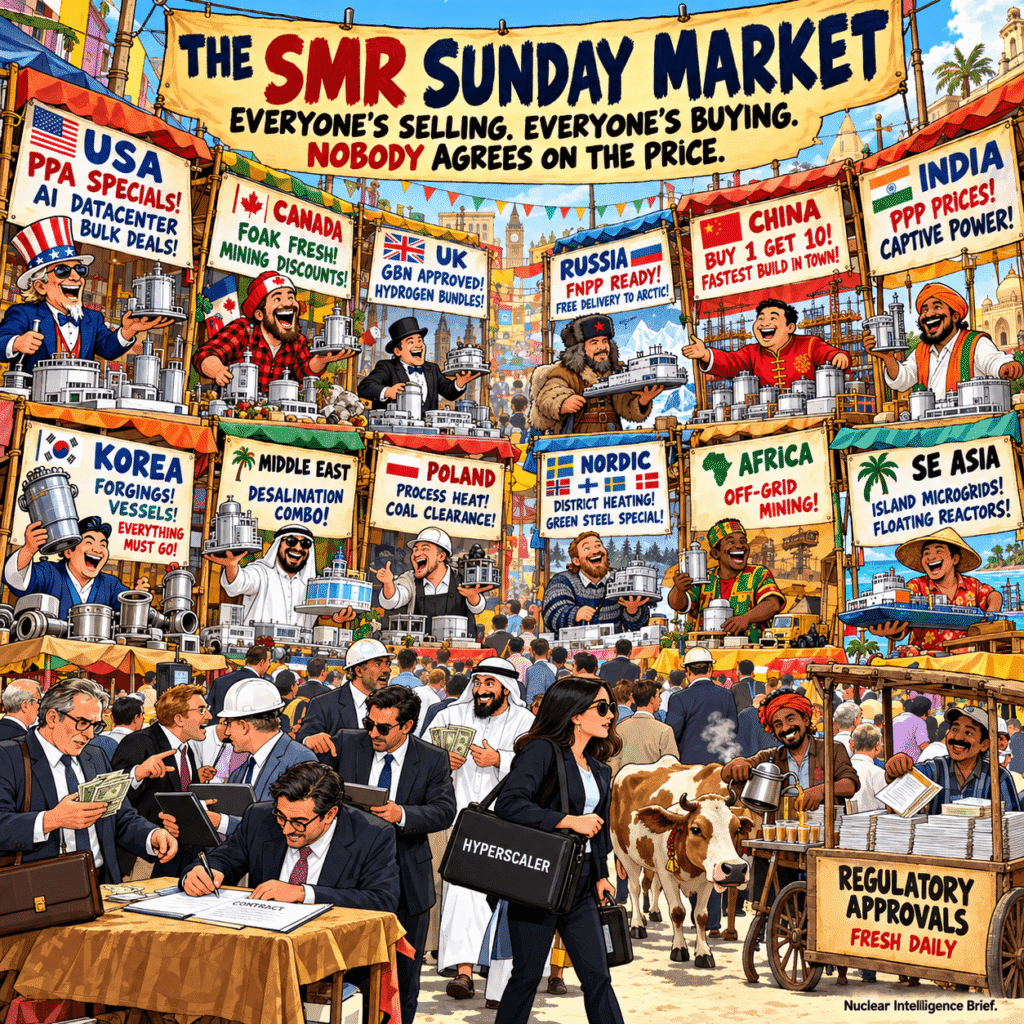
The deployment landscape for Small Modular Reactors (SMRs) is shifting rapidly from theoretical project conceptualization to site preparation, regulatory licensing, and active commercial deployment. While early market entry was characterized by public-sector research grants, current commercial momentum is driven by hyperscale AI/data center power demands, coal-to-nuclear repowering initiatives, off-grid industrial decarbonization, and cross-border state-backed export financing. A multi-regional market dynamic is emerging where vendor selection, supply chain allocation, and project economics are defined by regional industrial policies and energy needs.
Primary Regional Growth Markets
United States
The American market is driven primarily by hyperscale AI data center operators seeking massive volumes of firm, 24/7 carbon-free electricity via direct corporate power purchase agreements (PPAs). This private sector demand operates alongside coal-to-nuclear repowering initiatives that leverage existing transmission and cooling infrastructure, backed by federal support through the Department of Energy Advanced Reactor Demonstration Program (ARDP) and Inflation Reduction Act tax credits. Commercial progress is characterized by private capital structures, utility power purchase agreements, and formal standard Design Acceptance applications moving through the U.S. Nuclear Regulatory Commission pipeline.
Russia
Russia represents one of the most operationally advanced SMR markets globally, anchored by a centralized state strategy aiming to deploy substantial domestic nuclear capacity alongside an aggressive global export pipeline. Primary domestic use cases focus on Arctic resource extraction, industrial expansion in isolated territories, and coastal mining operations using operational floating nuclear power plants (FNPPs) like the Akademik Lomonosov alongside land-based designs such as the RITM-200 series. Deployed via Rosatom, the market operates under a vertically integrated model combining technology ownership, state-backed capital, and integrated fuel lifecycle services.
African Continent (South Africa, Rwanda, Ghana, Egypt)
African markets are emerging as primary targets for modular nuclear deployment due to severe regional grid capacity deficits, rapid industrialization demands, and widespread off-grid mining operations. Given that standard multi-gigawatt nuclear plants often exceed the load limits of regional transmission networks, SMRs offer a rightsized solution for captive industrial power, grid-scale baseload replacement, and energy-intensive seawater desalination. Deployment across the continent is largely driven by intergovernmental bilateral agreements (IGAs), turn-key vendor export frameworks from state-backed developers, and a resurgence in domestic strategic initiatives such as South Africa’s pebble-bed modular technology roadmap.
Canada
Canada has positioned itself as a primary Western hub for First-of-a-Kind (FOAK) utility-scale SMR execution, supported by coordinated interprovincial strategic deployment roadmaps across Ontario, Saskatchewan, New Brunswick, and Alberta. Key deployment focuses include on-grid utility capacity expansion, such as Ontario Power Generation’s Darlington New Nuclear Project, alongside off-grid mining decarbonization and high-temperature thermal supply for the oil sands sector. The market benefits from a streamlined Canadian Nuclear Safety Commission (CNSC) Vendor Design Review process and proactive federal clean technology investment policies.
Central & Eastern Europe (Poland, Czech Republic, Romania)
Central and Eastern European nations are aggressively evaluating SMRs to accelerate coal phase-outs, secure energy independence, and fulfill heavy industrial decarbonization mandates. The primary commercial opportunity in this region lies in providing direct high-temperature process heat and dedicated captive power for energy-intensive sectors like chemicals, steel, and paper production, as well as municipal district space heating. Private capital plays an unusually prominent role here, with large industrial conglomerates establishing direct joint ventures with Western SMR technology providers to secure long-term energy supplies.
United Kingdom
The UK nuclear landscape is defined by the Great British Nuclear (GBN) competitive selection program, which aims to co-fund and de-risk promising vendor designs to meet long-term net-zero grid targets. SMR applications in the UK focus on replacing retiring Advanced Gas-cooled Reactors (AGRs), powering green hydrogen production facilities, and supporting regional industrial heating networks. Development dynamics center on a mix of domestic consortia and international reactor vendors navigating regulatory approval under the Office for Nuclear Regulation (ONR).
India
India’s civil nuclear framework is undergoing a major structural shift as policy reforms open the door for private sector participation, co-investment, and non-utility commercial models. Driven by rapid national energy demand growth and industrial carbon-reduction goals, domestic research bodies are scaling indigenous designs like the BSMR-200 and BARC SMR-55. The market focus centers on providing dedicated captive power to heavy industrial complexes in steel, aluminum, and chemical manufacturing, transitioning the domestic nuclear sector from a historic state monopoly toward public-private partnership (PPP) structures.
South Korea
South Korea operates as both a domestic deployment target and a critical global manufacturing partner, supported by state-backed R&D into indigenous reactor concepts like the i-SMR and SMART designs. SMR use cases in South Korea prioritize combined power generation, high-temperature industrial steam, and export-focused modular fabrication. The domestic market is uniquely characterized by its deeply integrated heavy manufacturing ecosystem—capable of producing heavy forgings, reactor pressure vessels, and specialized components required by global vendors.
Nordic Region (Finland, Sweden)
Nordic markets are distinguished by high public support for nuclear energy, mature power grids, and an urgent requirement for fossil-free high-temperature thermal energy. Modernized regulatory frameworks in Finland and Sweden are increasingly adapting to accommodate multi-reactor sites and simplified urban zoning. Key applications include replacing fossil fuels in municipal district space heating networks and powering energy-dense heavy manufacturing processes, such as green steel, mining, and pulp and paper processing.
China
China leads global build speed through strong central planning, domestic supply chain standardization, and active operational demonstration facilities, such as the ACP100 Linglong One reactor. Primary deployment cases include coastal power generation, industrial steam supply, island microgrids, and large-scale district heating. Supported by state financing and a fully localized nuclear engineering sector, China’s SMR market is characterized by rapid, standardized fleet construction cycles.
Middle East (UAE, Saudi Arabia, Jordan)
Middle Eastern nations are pursuing SMRs as part of broader sovereign strategies to diversify energy mixes, preserve oil for export, and resolve extreme water scarcity. The primary operational requirement in these markets is dual-purpose co-generation, where high-temperature reactor output powers large-scale seawater desalination plants while delivering stable electricity to municipal grids and petroleum refineries. Capital-rich sovereign entities favor turn-key Build-Own-Operate (BOO) or Engineering, Procurement, and Construction (EPC) delivery models backed by comprehensive state-to-state vendor guarantees.
Southeast Asia (Indonesia, Philippines, Malaysia, Vietnam)
Southeast Asian island and coastal nations face distinct geographical constraints that make conventional large-scale nuclear power grids difficult to implement. SMRs and floating nuclear power plants (FNPPs) offer a flexible alternative to deliver stable baseload electricity to isolated island grids, remote industrial processing hubs, and off-grid mining sites. High electricity growth rates and fossil fuel replacement goals make the region a target for microreactors (under 100 MWe) and floating reactor concepts, with project development currently advancing through site characterization and regulatory capacity-building programs.
Save time and stay ahead—explore the SMR Market Intelligence Report 2027 for a concise breakdown of key market trends and projections.