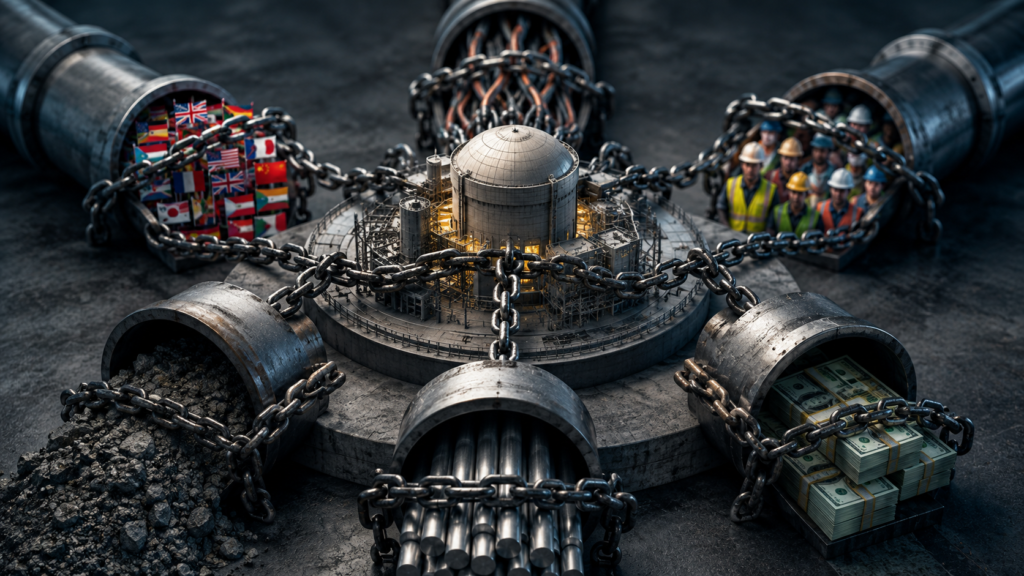
The global Small Modular Reactor (SMR) market has transitioned from an advanced nuclear engineering concept into an industrial deployment race. Valued at $4.8 billion in 2025, the market is projected to expand to $26.4 billion by 2034 at a compound annual growth rate (CAGR) of 19.3%, underlying a broader 700 GW, $0.5 trillion to $1.5 trillion market buildout opportunity through 2050. Driven by the continuous baseload electricity requirements of artificial intelligence data centers, sovereign energy security demands, and industrial re-industrialization, SMR technology offers high-density, zero-carbon power. However, commercial leadership will not be decided by core reactor physics or thermal efficiency. SMR developers face five critical operational, financial, and regulatory bottlenecks that will dictate capital deployment velocity, project bankability, and enterprise value creation.
Bottleneck 1: Capital Structure and Mass Production Economics
Unlike traditional gigawatt-scale power plants that utilize spatial scale to minimize per-kilowatt capital costs, SMRs incur higher initial normalized overnight construction costs (OCC). SMR developers must overcome this scale penalty by driving aggressive learning curves through standardized factory manufacturing. At a projected 15% learning rate, deploying 32 standardized SMR units yields a 55.6% reduction in overnight construction costs. Under standard scaling models, an SMR vendor must manufacture approximately eight 300 MWe units to achieve unit-cost parity with a single 1,000 MWe conventional reactor. First-of-a-kind (FOAK) capital costs remain high, ranging from $6,000 to $8,000+ per kilowatt with initial Levelized Cost of Electricity (LCOE) near $180/MWh. To survive until Nth-of-a-kind (NOAK) target costs of $40–$70/MWh are achieved, SMR companies require substantial financial runways. Vendors backed by sovereign credit facilities—such as Rolls-Royce SMR’s £599 million UK National Wealth Fund loan—or corporate hyperscalers offering $107–$130/MWh willingness-to-pay are uniquely positioned to navigate FOAK cash burn.
Bottleneck 2: Fuel Cycle Security and HALEU Availability
Fuel cycle architectures present a major strategic divide across SMR designs. Generation III+ water-cooled SMRs utilize conventional Low-Enriched Uranium (LEU, enriched up to 5% U-235), leveraging mature commercial supply chains. Conversely, Generation IV concepts—including High-Temperature Gas-Cooled and Molten Salt Reactors—depend on High-Assay Low-Enriched Uranium (HALEU, enriched between 5% and 19.75% U-235) to maintain high power density and extended refueling cycles. With fuel representing 8% to 27% of total nuclear LCOE, fuel security is critical to long-term project bankability. Commercial HALEU enrichment capacity is highly concentrated globally, creating an immediate supply chain constraint. Although government initiatives, such as the US Department of Energy’s $2.7 billion HALEU procurement program, aim to build domestic enrichment infrastructure, SMR developers without binding long-term fuel off-take contracts face severe commercial deployment risks.
Bottleneck 3: Licensing Velocity and Regulatory Harmonization
Legacy regulatory frameworks were structured around bespoke, site-specific gigawatt civil engineering projects rather than standardized, factory-fabricated products. While standard Nuclear Regulatory Commission (NRC) review cycles for pre-approved designs target 18 to 24 months, novel non-light-water SMR designs frequently encounter extended licensing review periods. Licensing delays inflate pre-construction capitalized owner costs and increase developer interest during construction. Furthermore, a lack of international regulatory harmonization forces developers to re-license standardized reactors across individual national jurisdictions, threatening to fragment mass-production assembly lines into costly, site-specific design modifications. Vendors possessing early design certifications—such as NuScale’s certified SMR design—or streamlined approval pathways hold a vital time-to-market advantage.
Bottleneck 4: Heavy Supply Chain and Heavy Forging Bottlenecks
The fabrication of SMR reactor pressure vessels (RPVs) from SA-508 Grade 3 steel relies on a concentrated global heavy forging capacity. Ultra-heavy forging facilities capable of handling large nuclear-grade ingots are limited globally to suppliers like Japan Steel Works (JSW), Doosan Heavy Industries, Framatome, and Sheffield Forgemasters. Historically, facilities like JSW produced only about four large pressure vessels per year, creating multi-year procurement queues. To resolve this bottleneck, advanced manufacturing technologies are essential. A major development is Local Electron-Beam Welding (LEBW), pioneered by Sheffield Forgemasters, which completes weld assemblies on 200 mm thick, 3-meter diameter nuclear-grade vessel sections in under 24 hours (or 140 minutes in a single pass)—a process traditionally requiring up to 12 months using multi-pass welding. SMR developers that integrate advanced manufacturing into their supply chain strategy will dramatically shorten delivery timelines.
Bottleneck 5: Grid Connection Queues and Offtake Architecture
Securing grid interconnection presents a significant commercial barrier due to multi-year transmission queue backlogs across major regional power markets, despite administrative reforms like FERC Order 2023. SMR developers are employing two primary strategies to circumvent grid queues. Reclaiming retired coal power sites through brownfield coal-to-nuclear repowering represents a 110 GW addressable market, utilizing existing high-voltage transmission rights, substations, and cooling infrastructure to save significant capital and study time. Alternatively, surging AI training loads requiring 50 to 500 MW per data center campus are driving direct Behind-the-Meter (BTM) hyperscaler colocation. BTM colocation bypasses public grid queues entirely, eliminates transmission losses, and provides SMR vendors with guaranteed long-term power purchase agreements.
| Bottleneck Category | Primary Operational Risk | Quantitative Benchmark / Metric | Strategic Winning Playbook |
| Capital & Cost Structure | High FOAK costs; scale penalty relative to large reactors. | FOAK LCOE ~$180/MWh vs. NOAK target $40–$70/MWh. | High manufacturing learning rates via serial factory production. |
| Fuel Cycle Infrastructure | Concentrated HALEU enrichment pipeline. | Fuel costs comprise 8%–27% of LCOE. | Binding long-term fuel off-take agreements & state co-funding (e.g., $2.7B US DOE program). |
| Licensing Velocity | Extended regulatory reviews; design fragmentation. | Pre-approved NRC target review of 18–24 months. | Strict design standardization and early regulatory design certification. |
| Heavy Supply Chain | Heavy forging queue for SA-508 RPV components. | JSW historical capacity ~$4 RPVs/year. | Advanced manufacturing adoption (e.g., LEBW reducing weld times from 12 months to <24 hours). |
| Grid Interconnection | Multi-year regional transmission queue backlogs. | 110 GW brownfield coal site potential; 50–500 MW AI load needs. | Behind-the-Meter hyperscaler colocation and brownfield coal-to-nuclear repowering. |
The commercial viability of SMR vendors will be determined by execution across these five operational bottlenecks rather than theoretical reactor performance. Winning companies will be distinguished by standardizing reactor designs to capture serial factory learning rates, securing domestic LEU or HALEU fuel supplies, integrating advanced manufacturing techniques like local electron-beam welding to bypass heavy forging queues, and anchoring revenue through direct Behind-the-Meter hyperscaler agreements or brownfield coal site reuse. Developers that master this capital, regulatory, and supply chain ecosystem will capture the majority of equity value in the expanding nuclear energy supercycle.
Get a copy of the SMR Market Intelligence Report 2027 to learn our forecast for the upcoming annual SMR market. It is concise, easy to scan, and effortless to understand.