The explosive acceleration of artificial intelligence computing has confronted technology hyperscalers with a fundamental physical bottleneck: regional electrical grid capacity. As global technology leaders execute over $650 billion in capital expenditures primarily directed toward AI infrastructure, server density has rapidly outstripped conventional power availability. Processing an AI workload requires roughly ten times the electricity of a standard search query, with an individual NVIDIA H100 GPU consuming 700 watts and a high-density 100,000-GPU cluster demanding 100 megawatts (MW) of continuous electricity.
Because AI workloads demand uninterrupted 24/7 power, relying solely on intermittent wind and solar generation has proven insufficient, driving corporate greenhouse gas emissions up by 29.1% at Microsoft and 48% at Google. With global data center power consumption projected to surge from 460 terawatt-hours (TWh) in 2024 to 1,300 TWh by 2035, access to firm, clean baseload electricity has become the premier competitive differentiator in tech site selection.
Emerging Deal Structures: From Long-Term Offtake to Balance-Sheet Underwriting
To resolve the power shortfall, hyperscalers are pioneering novel contracting mechanisms that pivot away from traditional spot-market energy procurement toward long-duration balance-sheet underwriting. Over 9.8 gigawatts (GW) of nuclear power capacity has already been contracted across multiple distinct deal structures designed to balance short-term power access against long-term operational scale.
| Deal Model | Mechanism & Asset Focus | Strategic Advantage | Landmark Industry Example |
| Plant Restarts & Uprates | Reactivating retired reactors or expanding existing plant capacity via long-term PPAs | Fastest path to firm gigawatt-scale power on existing grid infrastructure | Microsoft / Constellation ($16B, 20-yr PPA for 835 MW TMI Unit 1 restart) |
| Co-Location (Behind-the-Meter) | Acquiring data center campuses physically adjacent to operating nuclear stations | Direct power delivery, bypassing long grid interconnection delays | Amazon / Talen Energy ($650M acquisition of 960 MW Susquehanna campus) |
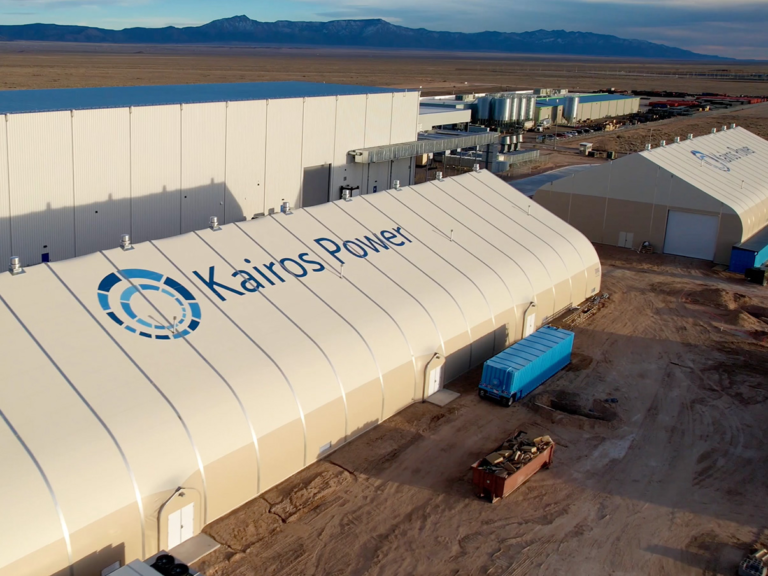
| Corporate SMR Fleets | Direct funding and offtake guarantees for multi-unit advanced reactor deployments | Scalable, modular capacity tailored to future power growth beyond 2030 | Google / Kairos Power (Up to 500 MW corporate fleet deployment) |
| Multi-Asset Portfolios | Aggregating operational generation, uprates, and SMR pipelines under unified procurement | Blends near-term energy delivery with long-term technology development | Meta / Vistra, TerraPower, & Oklo (6.6 GW multi-partner portfolio) |
Corporate Positioning across the Nuclear Supply Chain
A clear competitive divide is emerging among technology giants, independent power producers, and advanced reactor developers. Power generators holding existing nuclear fleets possess high strategic leverage. Constellation Energy expanded its corporate presence through landmark agreements with Microsoft for the 835 MW Crane Clean Energy Center and Meta for the 1,121 MW Clinton Clean Energy Center. Similarly, Vistra contracted 2.6 GW of power to Meta from its Perry, Davis-Besse, and Beaver Valley operational plants, supported by 433 MW in corporate-funded capacity uprates.
Simultaneously, specialized nuclear innovators are commercializing next-generation technologies through hyperscaler backing. Startup developers including Kairos Power, X-energy, TerraPower, and Oklo have secured multi-gigawatt commitments that accelerate their commercialization roadmaps. Hyperscalers are not merely purchasing electricity; they are acting as primary market-makers that dictate which technologies, developers, and regional hubs advance to commercial scale.
Rewriting Project Economics and Risk Allocations
Historically, nuclear projects faced severe financial friction due to massive upfront capital intensity, regulatory uncertainty, and long payback periods. Public utilities relied on government subsidies or rate-basing costs onto retail consumers, often leading to project cancellations during cost overruns. Tech hyperscalers are fundamentally altering this financial equation by providing corporate-backed, 20-year Power Purchase Agreements that offer unprecedented revenue certainty for institutional lenders and equity investors.
In advanced reactor deployments, innovative risk-sharing models are protecting ratepayers while de-risking technology. Under the agreement between Google, Kairos Power, and the Tennessee Valley Authority, the tech enterprise and developer absorb first-of-a-kind (FOAK) development costs, while the utility provides a stable PPA off-take structure. By funding initial deployment phases, hyperscalers accelerate the industry along the cost curve toward standardized, Nth-of-a-kind (NOAK) manufacturing economics. This capital injection translates into substantial asset premiums, with nuclear-connected data center sites commanding lease rates 15% to 25% higher than traditional grid-constrained alternatives.
The Expanding Scope of Small Modular Reactors
Small Modular Reactors (SMRs) represent the long-term solution for scalable, high-density computing loads. Unlike traditional gigawatt-scale plants that require decade-long construction timelines and massive geographic footprints, SMRs offer factory-built, modular designs ranging from 50 MW to 345 MW per unit. Advanced coolant architectures—such as Kairos Power’s molten-salt pebble-bed technology, TerraPower’s liquid-sodium Natrium system, and Oklo’s Aurora fast reactor—provide enhanced safety profiles and operational flexibility. SMRs can also integrate thermal energy storage, as demonstrated by TerraPower’s Natrium system, which pairs 345 MW of baseload capacity with a molten-salt thermal storage system capable of flexing output to 500 MW to balance regional grid fluctuations.
Market Implications and Strategic Execution Risks
The integration of technology balance sheets into energy markets carries profound implications for power utilities, grid operators, and digital infrastructure developers. The movement toward “Bring Your Own Power” (BYOP) data center development reflects growing institutional impatience with public interconnection queues, such as the PJM Interconnection queue where over 300 GW of projects face multi-year delays.
However, execution risks remain significant. Regulatory scrutiny is rising, as evidenced by the Federal Energy Regulatory Commission (FERC) rejecting an expanded interconnection agreement for Amazon’s Susquehanna co-located campus due to concerns regarding grid cost-shifting and reliability. Furthermore, advanced reactors face licensing delays at the Nuclear Regulatory Commission (NRC) and bottlenecked supply chains for High-Assay Low-Enriched Uranium (HALEU) fuel. Despite these headwinds, hyperscalers’ multi-decade capital commitments ensure that nuclear power will remain the cornerstone of clean energy infrastructure for the artificial intelligence era.
Get a copy of the SMR Market Intelligence Report 2027 to learn our forecast for the upcoming annual SMR market. It is concise, easy to scan, and effortless to understand.