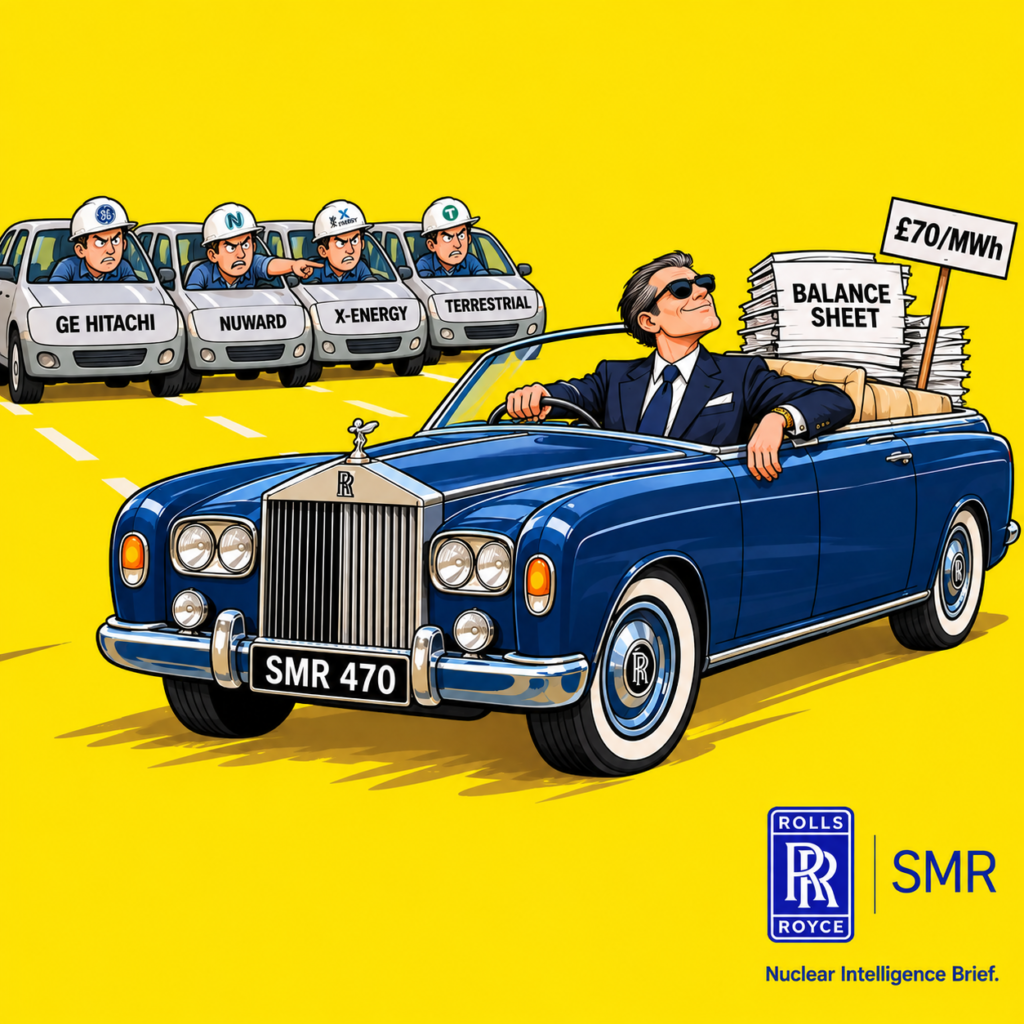
Nuclear power never failed because of engineering. It failed because of money.
Decades of multi-billion-pound overruns, decade-long delays, and crippling debt-servicing costs during construction have made gigawatt-scale reactors unbankable for private capital. The problem isn’t the reactor. The problem is the financial architecture around it.
Rolls-Royce SMR is engineered to disrupt that architecture—not by building a better reactor, but by treating nuclear power as an industrialized, factory-manufactured capital asset rather than a bespoke, on-site civil megaproject. The target: a standardized 470 MWe pressurized water reactor delivering power below an estimated £70 per megawatt-hour, decoupled from state-guaranteed balance-sheet bailouts.
The 470 MWe Sweet Spot
The deliberate sizing of the unit at 470 MWe occupies an intentional gap in power generation economics. Unlike microreactors or sub-300 MWe platforms such as GE Hitachi’s BWRX-300, Rolls-Royce balances thermodynamic economies of scale against the physical constraints of terrestrial logistics.
Every primary module is engineered to remain transportable across standard road networks—circumventing the coastal and heavy-barge shipping requirements that limit gigawatt-scale siting. Sized to power roughly one million homes on one-tenth the footprint of a conventional station, each unit carries an estimated overnight capital cost of £2–3 billion. That brings individual procurement well within the financing parameters of commercial utilities and heavy industrial consortia.
Syndicated Equity, Insulated Parent
To protect the parent conglomerate from financial contagion, Rolls-Royce structured the entity as a standalone special purpose vehicle backed by syndicated institutional equity.
The venture was seeded with £210 million in public grant funding from UK Research and Innovation, then matched with equity from a coalition including US nuclear operator Constellation Energy and investment fund BNF Resources. The Qatar Investment Authority later injected £85 million, followed by a late-2024 transaction in which Czech utility ČEZ acquired a 20 percent equity stake.
That ownership design does two things. It cushions the parent company’s credit rating. And it converts sovereign wealth funds and commercial operators into direct equity partners with a vested interest in project delivery.
Capital Discipline and the Asset-Light Pivot
The subsidiary’s corporate strategy hardened after Tufan Erginbilgic became Chief Executive of Rolls-Royce Holdings. Enforcing rigorous capital allocation across the group, Erginbilgic replaced the subsidiary’s early leadership with Group President Chris Cholerton and demanded strict performance management.
The most significant shift: Rolls-Royce dropped its initial plans to build proprietary forging facilities for reactor pressure vessels. Instead, it pivoted to third-party procurement from established suppliers such as Sheffield Forgemasters. That transition—from asset-heavy manufacturer to integrated supply-chain orchestrator—curbed internal cash burn while protecting the parent company’s free cash flow targets.
The Factory Model
The economic engine of the business is a production architecture that moves 90 percent of plant construction off-site into centralized, automated factories. The facility is segmented into roughly 1,500 standardized, transportable modules—fabricated, outfitted with instrumentation, and quality-tested in factory clean rooms before shipment.
On site, civil assembly takes place under a temporary, weather-sealed canopy that shields workers and concrete from the elements. Unpredictable outdoor construction becomes a predictable mechanical assembly line. The process is designed to compress on-site construction to roughly four years—collapsing capitalized interest during construction, the historic trigger for nuclear utility credit downgrades, and giving institutional financiers a bankable completion schedule.
Regulatory Velocity as a Moat
In commercial nuclear development, regulatory velocity is the primary barrier to entry. Rolls-Royce SMR has turned early regulatory milestones into an operational moat across European markets.
Under the UK’s modernized Generic Design Assessment, the platform cleared Step 1 in early 2023 and became the first small modular reactor to complete Step 2 safety and security reviews in July 2024. It is now advancing through the final Step 3 detailed assessment, targeting completion in 2026—an estimated eighteen-month head start over foreign competitors in the domestic market.
That regulatory progression secured Rolls-Royce’s selection as the preferred vendor for Great British Nuclear’s procurement program, opening access to site allocations and multi-billion-pound state funding frameworks.
Bankable Export Momentum
Domestic regulatory footing has translated into bankable export momentum across Continental Europe, where energy security concerns and coal-decommissioning timelines have aligned.
ČEZ’s multi-hundred-million-pound investment came with a deployment roadmap targeting up to 3 gigawatts of capacity in the Czech Republic—repowering coal sites such as Tušimice and expanding output alongside existing units at Temelín. In Sweden, energy project Videberg Kraft—backed by Vattenfall and industrial consortium Industrikraft—selected Rolls-Royce SMR in mid-2026 for a three-unit installation on the Värö Peninsula, down-selecting it over GE Hitachi’s platform.
By offering a European supply base capable of delivering over 80 percent domestic or regional industrial content, Rolls-Royce has insulated European customers from transatlantic supply bottlenecks.
The Factory-Utilization Paradox
Despite these commercial agreements, Rolls-Royce SMR must navigate the factory-utilization paradox inherent to modular manufacturing.
The low unit costs promised by serial modularization depend entirely on steady, high-volume production through dedicated factory lines. But private industrial consortia cannot commit capital to high-throughput assembly lines without binding offtake orders. And risk-averse utility boards hesitate to finalize procurement contracts until operational factory lines have proven unit costs.
Overcoming that capitalization dilemma requires public-private risk-sharing during first-of-a-kind production. The commercial viability of the initial fleet relies on revenue-stabilizing frameworks such as Contracts for Difference and the Regulated Asset Base model, backed by targeted equity from state institutions like the UK National Wealth Fund.
The Behind-the-Meter Demand Shift
The demand profile for firm, zero-carbon power is shifting as tech hyperscalers and energy-intensive manufacturing face systemic grid congestion. The power demands of AI clusters and advanced manufacturing are outpacing local grid capacity, accelerating demand for dedicated behind-the-meter generation.
At 470 MWe, the Rolls-Royce SMR matches the continuous baseload demand of large-scale data center parks without requiring massive regional transmission expansions. Unlike smaller microreactors that need complex multi-unit arrays to reach equivalent capacity, a single Rolls-Royce installation provides dense, uninterruptible power at a capital expense accessible to large corporate tech balance sheets.
What Actually Decides This
The long-term viability of Rolls-Royce SMR will be decided by industrial execution, not nuclear physics.
The company has built a defensible corporate structure: syndicated equity, an asset-light procurement model, and advanced regulatory milestones across Northern Europe. The defining challenge over the next decade will be maintaining schedule discipline and manufacturing tolerances as initial module fabrication begins—avoiding the quality defects and supply-chain friction that have derailed Western nuclear builds for forty years.
If Rolls-Royce can demonstrate that atomic generation can be delivered with the cost certainty, volume efficiency, and predictability of advanced aerospace engineering, it will transform nuclear power from an unpredictable financial liability into an investable, standardized infrastructure asset class.
That transformation is what we track—developer by developer, in the SMR Market Intelligence Report 2027.